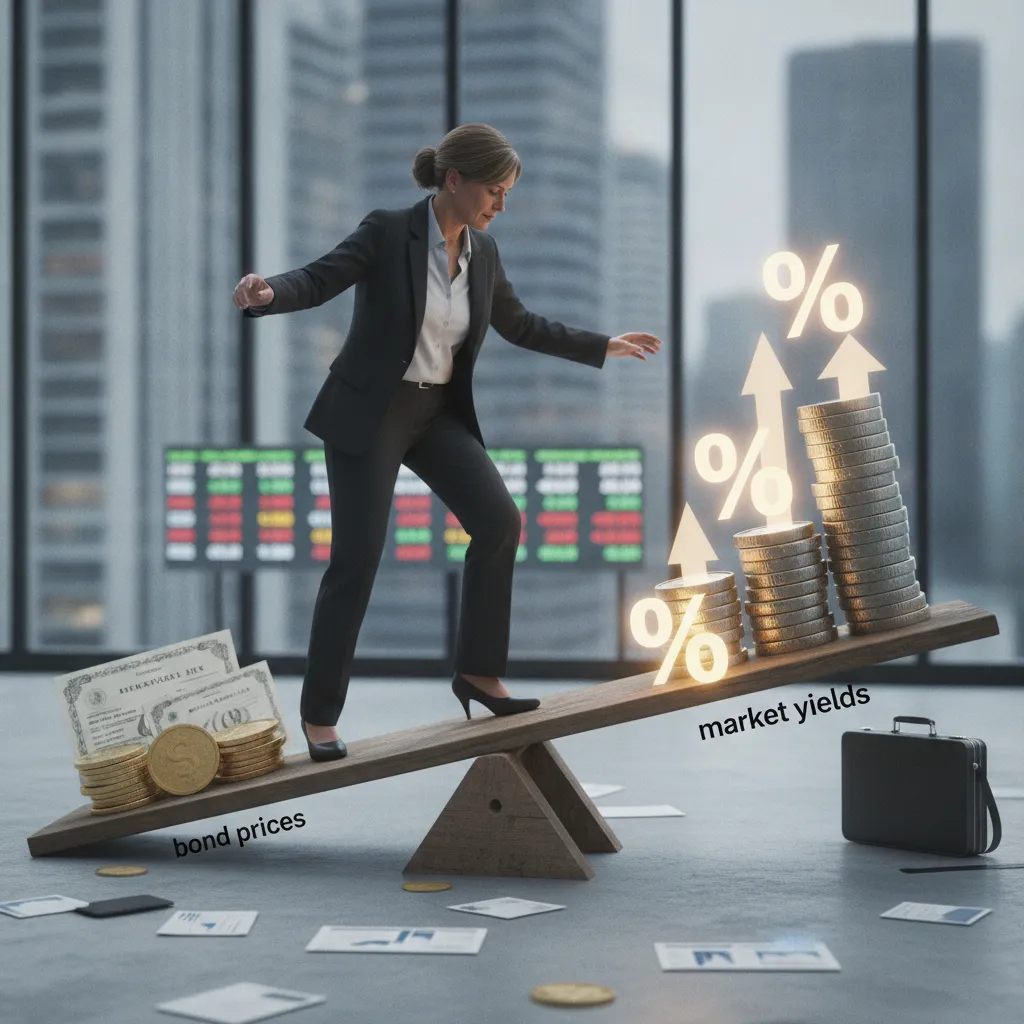
Navigating the world of bonds often feels like balancing on a teeter totter, according to Morningstar portfolio strategist Amy Arnott. In a recent discussion regarding her Ask the Analyst column, Arnott explained that the fundamental relationship between bond prices and market yields remains inverse. When yields climb, existing bond prices drop because newer issues offer better returns, making older ones less attractive. While this can lead to short term losses for those holding bond ETFs, Arnott noted that managers can eventually offset these dips by reinvesting maturing funds into higher yielding securities.
For investors weighing their options over a five year horizon, the choice typically boils down to Treasury bonds, I bonds, or Treasury Inflation Protected Securities known as TIPS. While standard Treasuries are prized for their simplicity and liquidity, they lack inherent protection against rising costs. Both I bonds and TIPS provide inflation safeguards, but they come with different hurdles. I bonds are capped at strict annual purchase limits, whereas TIPS allow for larger investments but introduce the headache of phantom income, meaning investors may owe taxes on inflation adjustments before they actually receive the cash. Because of this tax drag, Arnott suggests keeping TIPS in tax deferred accounts.
The conversation also touched upon the psychological toll of market volatility, particularly for retirees. One example involved an elderly investor facing significant paper losses in municipal bond funds following Federal Reserve rate hikes. Arnott expressed concern when conservative investors are placed in high sensitivity products they cannot stomach during downturns. Her advice for those feeling the pinch is to seek out shorter duration funds that are less reactive to interest rate swings rather than simply waiting indefinitely to break even on volatile holdings.
Beyond choosing specific assets, where an investor stores their bonds can be just as critical as what they buy. When deciding between a Roth and a traditional IRA, Arnott recommends favoring the traditional IRA for fixed income. Since Roth IRAs offer permanent tax free growth, that valuable space is best reserved for high growth assets like stocks. By placing lower yield bonds in a traditional account instead, investors maximize the long term efficiency of their entire portfolio structure.